Crypto screens often show two prices for what looks like the same coin. One is a spot price. One is a perpetual futures price. They sit near each other so often that the labels start to look decorative. They are different claims, with different counterparties and different ways of being wrong.
Spot is a trade in the asset
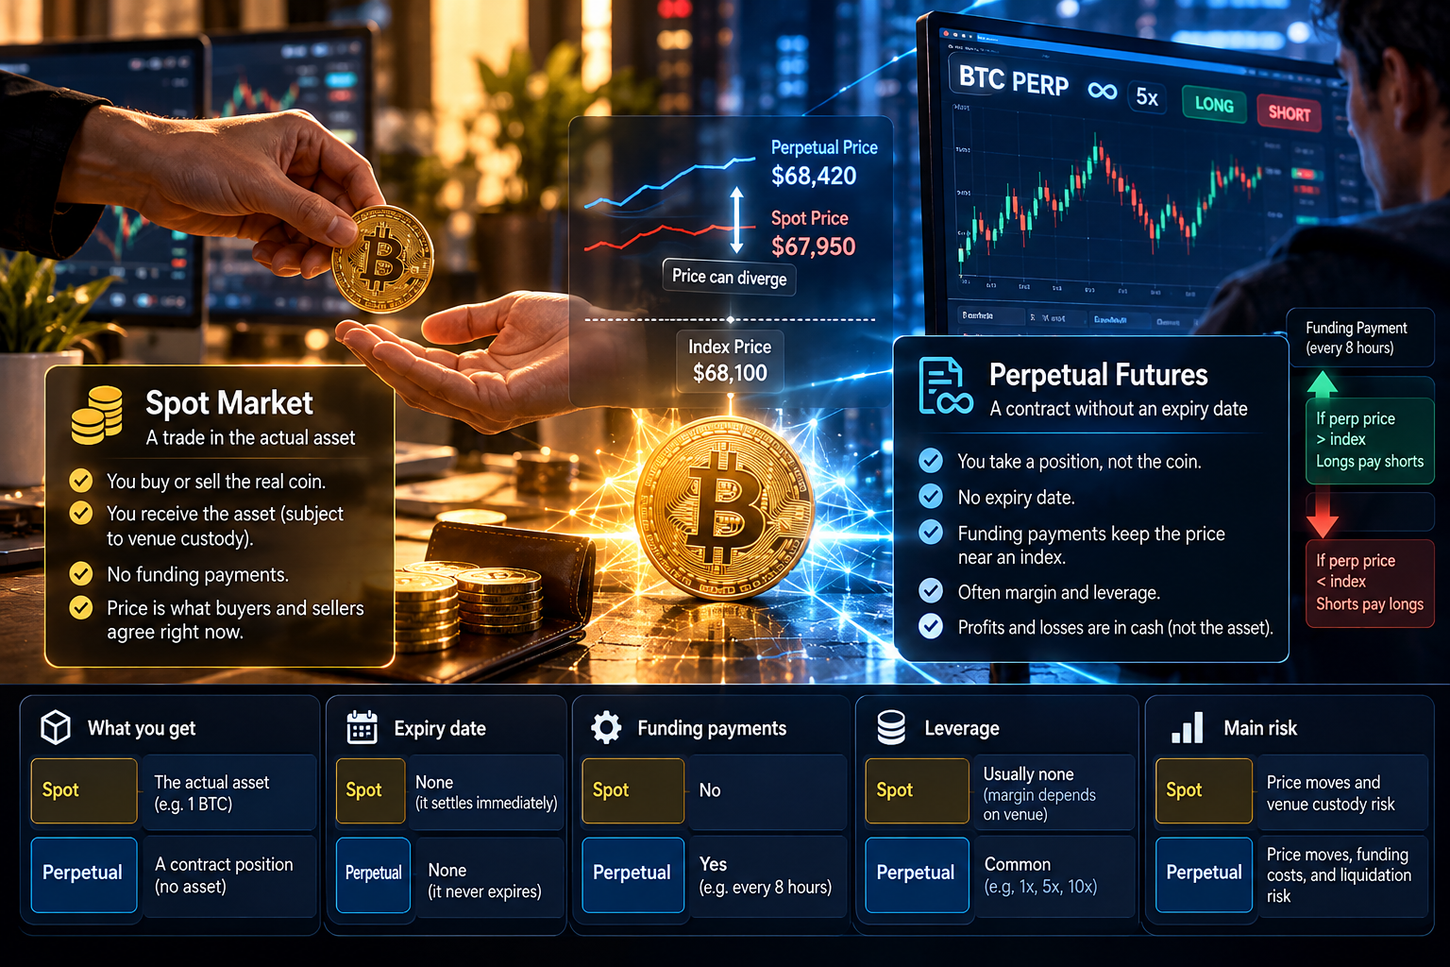
A spot market is where the asset itself is exchanged. On a bitcoin spot market, the buyer’s claim is to bitcoin, subject to the venue’s custody and settlement rules, or to a direct on-chain transfer if the trade is peer to peer. When the trade settles, the buyer has the coins or a claim on the venue for the coins. The seller has the money. There is no funding payment later to keep the trade “on index.” The price is simply what those two sides agreed.
A perpetual is a contract without a date
A conventional future expires. At expiry, the contract price converges because the contract becomes a claim to the spot delivery terms. A perpetual future, also called a perpetual swap, has no expiry. That design was set out for bitcoin by BitMEX in its perpetual-contracts documentation: the contract does not settle on a calendar date, and a funding payment between longs and shorts pulls the contract price toward a spot index.
The funding rate is the size and direction of that payment. If the perpetual trades above the index, longs typically pay shorts. If it trades below, shorts typically pay longs. The payment is not a dividend from a company and it is not interest from the Bitcoin protocol. It is a transfer between the contract’s counterparties, defined by the venue. You can hold a perpetual and never touch a coin. You can also lose more than a spot holder in the same price move if the contract is leveraged, because the venue will liquidate a position whose margin is gone.
What a gap between them means
A small gap is ordinary. A large gap means the contract market and the spot market are disagreeing, and funding is the mechanism that makes the disagreement expensive to hold. It does not mean the spot coins have changed. It does not mean an index has failed. It means leveraged demand is leaning to one side.
Read a screen by asking what would actually be delivered. Spot delivers the asset, subject to the venue. A perpetual delivers cash flows defined by the contract: margin, funding, and a price that is marked to an index. Strategies that mix them are real, but the sentence “the bitcoin price” should say which of the two claims it is quoting.
Leverage is a term in the contract
Spot exposure is limited to the coins you paid for, plus whatever credit a particular venue has extended under its own rules. A perpetual is routinely margined. The venue computes a mark price, compares it with your margin, and liquidates the position when the contract says the margin is insufficient. That liquidation is not the Bitcoin network seizing coins. It is the venue closing a contract so the rest of the book still clears. The price at which it closes can be worse than the mark you were watching, because the contract says how liquidation orders are placed. Two traders who both say they are “long bitcoin” can be in completely different instruments, one of which can be closed by a machine overnight and one of which cannot.
Funding is the carrying cost that makes this sustainable for the venue. It is not a detail to add later. A perpetual that trades above the spot index charges the long side, in the usual design, so that the rich price is expensive to hold. The spot holder has no such payment. Over a week of elevated funding, the perpetual long and the spot holder with the same notional size have not had the same result even if the index is unchanged. Comparing their profit-and-loss without the funding line is how the two markets get described as one price.
Sources
- BitMEX, perpetual contracts guide, the public description of a perpetual swap and its funding mechanism.
- CF Benchmarks documentation, examples of the spot indexes that futures contracts reference.