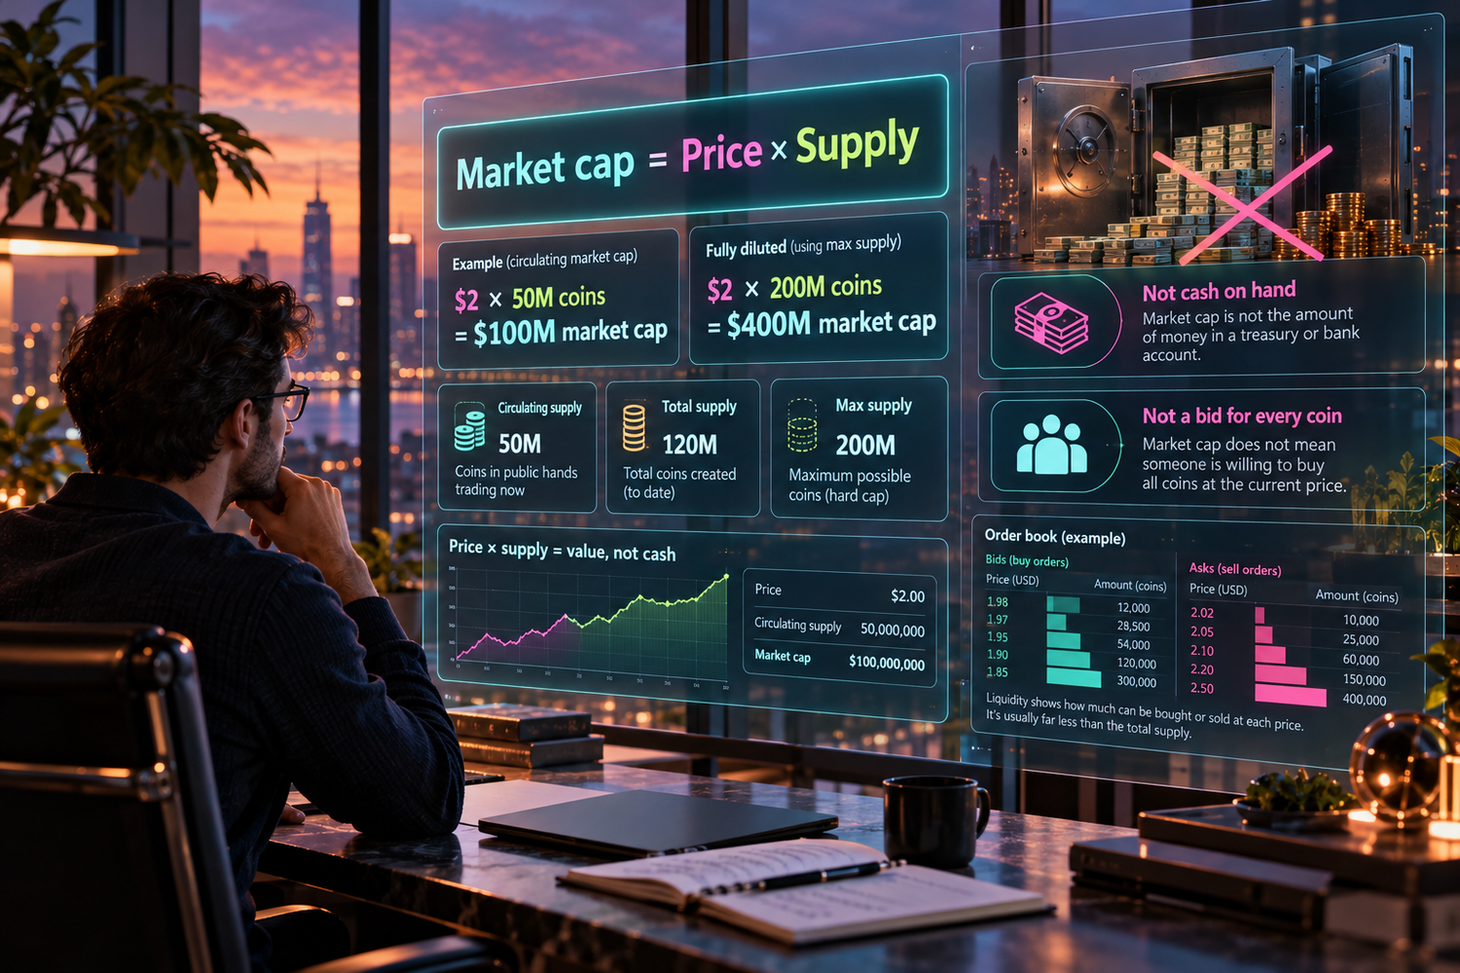
Market capitalization is a multiplication. Take a price and multiply it by a measure of supply. The result is a number in dollars, or another unit of account, that lets people compare assets of different prices and different supplies. It is not a pile of money sitting somewhere, and it is not what the holders could raise if they all sold.
Which price, which supply
The price in the formula is a market price, usually a recent trade or an index of trades. It is the price of the coins that actually changed hands, not a bid that covers the entire supply. The supply figure depends on the compiler. Circulating supply tries to count coins that are available to the market. Total supply may include coins that exist but are locked, vesting, or sitting in a contract the compiler treats as not circulating. Maximum supply is a protocol or project cap, including coins that do not exist yet.
Those choices change the product. Two sites can publish two market caps for the same asset on the same day because they disagree about the float, or because they use different prices. Neither number is a bank balance. Bitcoin’s protocol cap, discussed in the halving schedule, is a rule about issuance. A market cap that uses a circulating figure near that cap is still just price times coins, not a claim that the network holds dollars.
Why the cash reading fails
If one coin trades at $100 and a compiler counts 1 million coins, the market cap is $100 million. That does not mean buyers have posted $100 million, or that sellers could receive $100 million. Selling a large fraction of the supply would trade against whatever bids exist. The price used in the formula would move. The multiplication does not include an order book.
The same mistake appears when a treasury or an issuer is described as “worth” the market cap. A project wallet that holds its own tokens is holding inventory valued at the current price. It is not holding the market cap in cash. A spot bitcoin fund that holds bitcoin has bitcoin, priced by the market, minus whatever fees and liabilities the fund’s own documents describe. The market cap of bitcoin is still not the fund’s cash.
Use the figure for what it is good for: a rough scale, and a way to see that price alone is a bad comparison across coins with different supplies. Then ask which price and which supply went into it. If the question is “how much money is there,” look at the bids, the volume, and the actual assets on a specific balance sheet. The market cap will not answer that question.
A multiplication you can do on paper
The arithmetic is easier to see with numbers that are obviously made up. Suppose a coin last traded at $2, and a compiler says 50 million coins are circulating. The circulating market cap is $100 million. Suppose the protocol allows 200 million coins eventually, and the compiler also prints a “fully diluted” figure using that cap. That second product is $400 million. Neither number is cash. The fully diluted figure counts coins that have not been issued. The circulating figure counts coins the compiler believes are in the float, at a price observed on the coins that actually traded. If the next trade is $1, both products fall by half and not a single coin has been destroyed.
Stablecoins make the same point from the other direction. A token designed to trade near one dollar can have a large market cap because the supply is large, not because a speculative bid appeared. Adding that supply into a “crypto market cap” total changes the total, and it changes bitcoin’s share of the total, without any change in bitcoin’s order book. The multiplication did what it always does. It just should not be narrated as money that can be picked up. A market cap answers “price times this supply.” It does not answer “cash the holders could raise.”
Sources
- Investopedia, market capitalization, on the price-times-supply definition in equity markets, which is the same arithmetic people then apply to coins.
- Bitcoin.org, Bitcoin halving, on the issuance cap as a protocol rule rather than a cash balance.